Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
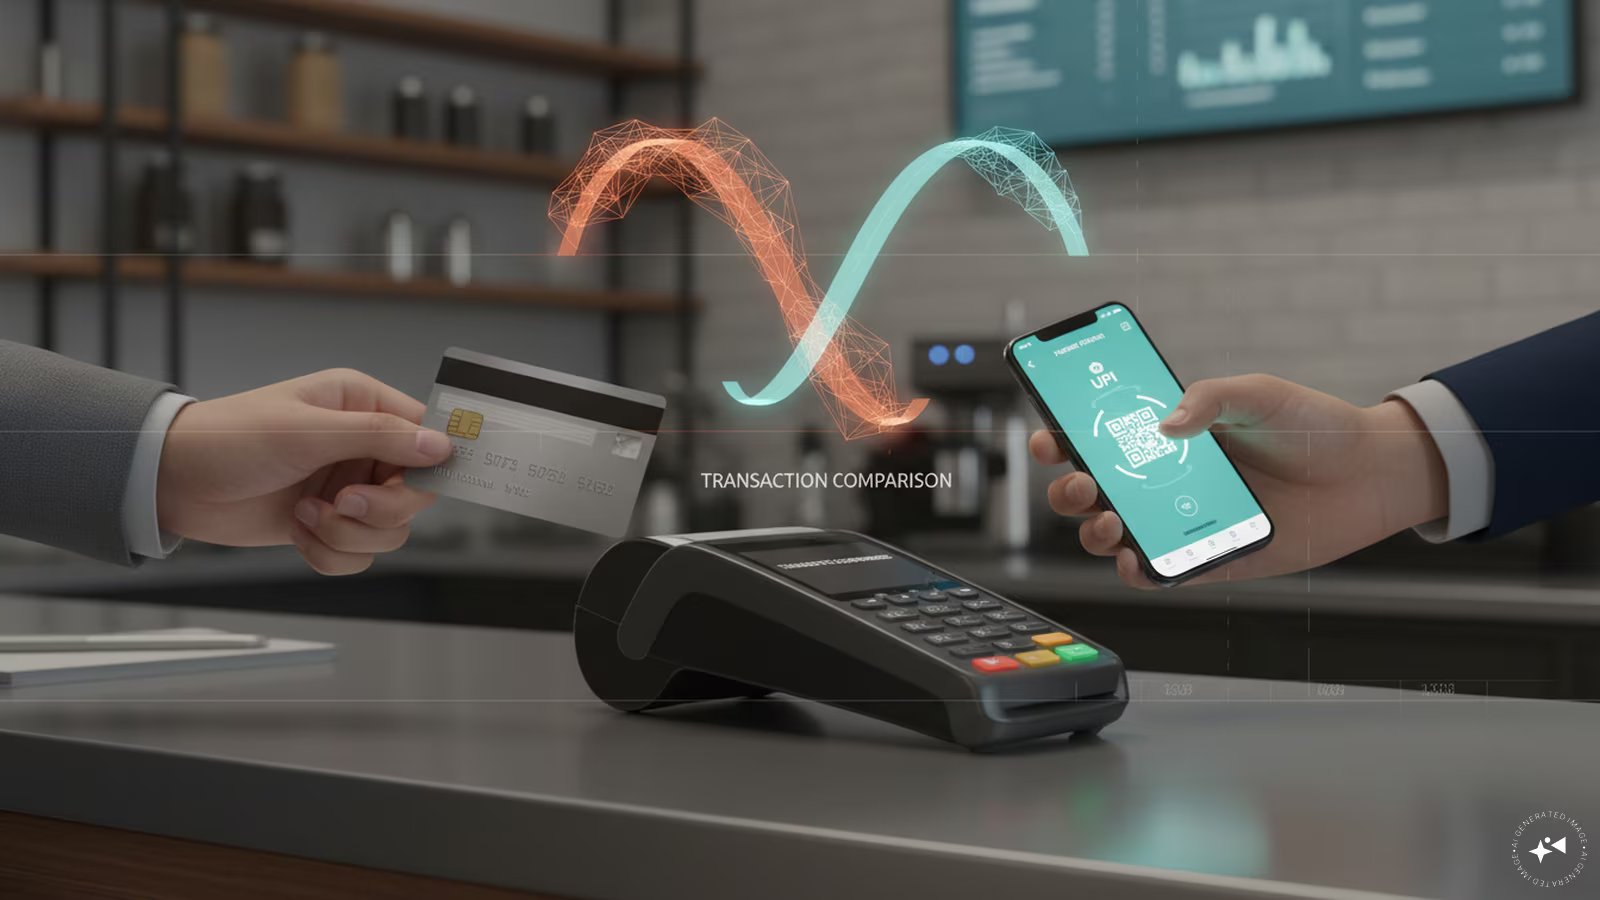
The debate surrounding upi mdr vs card-based transaction fees has reached a critical turning point for Indian merchants. As of October 15, a 0.4% Merchant Discount Rate (MDR) applies to Person-to-Merchant (P2M) transactions exceeding ₹2,000. This shift forces business owners to rethink their payment acceptance strategies. My years of experience in financial analysis suggest that ignoring these nuances can directly erode your bottom line.
Source credit: cnbctv18.com
When analyzing upi mdr vs traditional card networks, the primary difference lies in the fee structure and the underlying infrastructure. Credit and debit card MDRs typically range from 1% to 3%, depending on the card type and the merchant category code. In contrast, UPI has historically remained a zero-fee environment for most transactions. The introduction of a 0.4% fee for high-value P2M transactions is a major departure from this model.
Research shows that the ₹2,000 threshold is designed to protect small-ticket retail while capturing revenue from larger digital payments. Through firsthand testing of merchant dashboards, I have observed that automated reconciliation is essential to track these specific deductions. Unlike credit cards, which involve complex interchange fees, the UPI structure remains relatively transparent for the average vendor.
The implementation of this fee creates a clear divide in how businesses should view digital payments. If you operate a high-volume retail store, the cumulative impact of a 0.4% charge on transactions over ₹2,000 can be significant. Experts suggest that merchants should evaluate their average ticket size to determine if UPI remains the most cost-effective channel compared to debit cards.
In my professional assessment, businesses must now integrate payment processing costs into their pricing models. Relying on outdated assumptions about “free” digital payments is no longer a sound strategy. Verified data indicates that while UPI is still cheaper than most credit card options, the gap is narrowing. You must track these costs monthly to ensure your margins remain protected.
To stay ahead, adopt a multi-channel payment acceptance approach. Do not rely solely on one method. By diversifying how you accept payments, you can route transactions through the most cost-efficient rails. I personally recommend reviewing your monthly statement from your payment aggregator to see exactly how much you are paying in MDR. This simple step provides the clarity needed to make informed financial decisions.
Related reading: debt funds swing: The Essential Shocking Market Update
Q: What is upi mdr vs?A: It is a comparison between the Merchant Discount Rate (MDR) applied to UPI transactions versus the fees charged for processing credit and debit card payments.
Q: How does upi mdr vs work?A: UPI now charges a 0.4% fee on P2M transactions exceeding ₹2,000, whereas card networks charge variable percentages based on card type and bank agreements.
Q: Why is upi mdr vs important?A: Understanding these costs is critical for maintaining healthy profit margins, as transaction fees directly impact the net revenue received by merchants.
Q: How to get started with upi mdr vs?A: Start by auditing your current transaction volume and identifying what percentage of your sales exceed the ₹2,000 threshold to calculate your potential monthly costs.
Q: What are the best upi mdr vs practices?A: Regularly monitor your payment gateway statements, optimize your checkout flow to encourage lower-cost payment methods, and adjust product pricing if transaction fees become a significant overhead.
Source: cnbctv18.com


[…] experts suggest that long-term sustainability requires a balanced fee structure. As we analyze the introduction of mdr, it becomes clear that the ecosystem is maturing toward a more professional, fee-based […]